
Life Insurance Coverage Ladder Estimator
This tool helps you estimate your total life insurance needs based on your debts, income, and future goals. It then suggests whether a single policy or a "laddered" approach (multiple policies with different terms) might be more cost-effective and flexible.
Strategy Comparison
Option 1: Single Large Policy
One policy covering all needs until retirement/age 65.
- Coverage:
- Term: 30 Years (Typical)
- Risk: Paying for coverage you may not need in later years.
Option 2: The Ladder Strategy (Recommended)
Multiple policies matching specific debt timelines.
Enter your financial details on the left to see your recommended coverage strategy.
You might think you can only have one life insurance policy because that’s how health insurance or car insurance often works. But here is the truth: multiple life insurance policies are not just allowed; they are common. There is no legal limit on how many policies a person can hold. Whether you buy two term policies from different companies or combine a term policy with a whole life plan, the choice is yours. The real question isn’t if you can do it, but whether you should.
Stacking coverage helps you match your protection to your actual financial needs without overpaying for a single massive policy. It lets you cover short-term debts like a mortgage separately from long-term goals like college funds. If you are wondering if this strategy fits your situation, keep reading. We will break down exactly how it works, when it makes sense, and where it might be a waste of money.
The Short Answer: Yes, You Can Stack Coverage
Insurance regulators do not cap the number of policies you own. They care about something else: insurable interest. This means you must prove that your death would cause a financial loss to someone else. As long as you can justify the total amount of coverage across all your policies, insurers will write them. For example, if you owe $400,000 on your house and want to leave $100,000 for your kids’ education, buying one $500,000 policy or two $250,000 policies achieves the same result. The difference lies in cost and flexibility.
Why would anyone split their coverage instead of buying one big policy? Usually, it comes down to price efficiency. Term life insurance rates jump significantly as the coverage amount increases. Buying two smaller policies can sometimes be cheaper than one large one, especially if you use term life insurance strategies like laddering. Additionally, splitting policies allows you to diversify risk. If one insurer goes bankrupt (rare, but possible), your beneficiaries still get paid by the other company.
Strategic Reasons to Buy Multiple Policies
Most people who hold more than one policy do so for specific strategic reasons. It is rarely random. Here are the most common scenarios where stacking makes sense.
Laddering Your Coverage
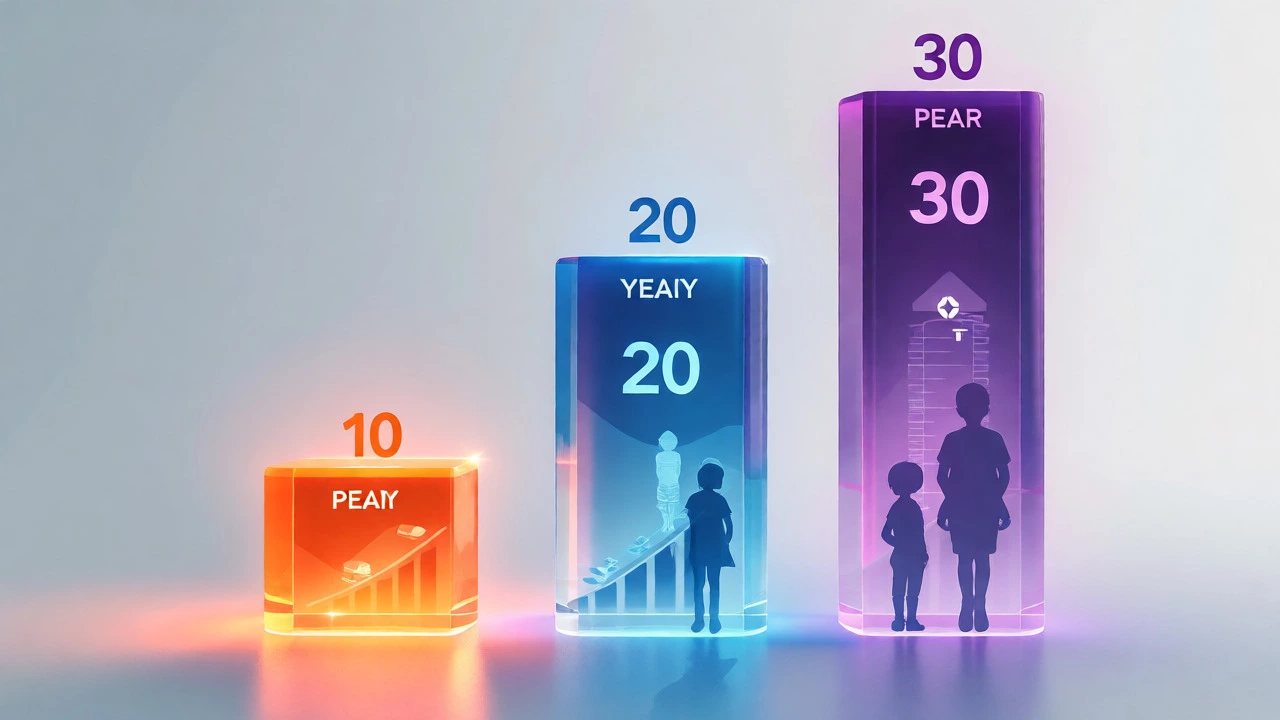
This is the most popular method for young families. You buy several term policies with different expiration dates. Imagine you need high coverage now because your kids are small and your mortgage is huge. In ten years, the mortgage will be smaller, and the kids will be older. You don’t need the same level of protection then.
- Policy A: $500,000 coverage for 10 years (covers early childhood expenses).
- Policy B: $300,000 coverage for 20 years (covers mid-life obligations).
- Policy C: $200,000 coverage for 30 years (covers retirement gaps or final expenses).
As each policy expires, your premium drops automatically because you shed the expensive, unnecessary coverage. You aren’t locked into paying for protection you no longer need.
Mixing Term and Permanent Life Insurance
Sometimes, you need both temporary and lifelong protection. You might buy a cheap term life insurance policy to cover your mortgage and daily income replacement. Then, you add a smaller permanent life insurance policy, like Whole Life or Universal Life, to cover funeral costs or estate taxes that won’t go away when you retire. This combo gives you affordable high-limit protection for the heavy lifting, plus guaranteed cash value growth for the long haul.
Employer vs. Individual Policies
A lot of employees rely solely on group life insurance provided by their job. This is risky. If you lose your job, you often lose that coverage too, or face skyrocketing conversion rates. Smart buyers treat employer coverage as a bonus. They buy a separate individual policy to ensure their family stays protected regardless of employment status. Technically, holding an employer group policy and a private individual policy counts as having two life insurance policies.
How Insurers Handle Multiple Applications
When you apply for a new policy while already holding others, the underwriter looks at your total aggregate coverage. They check your net worth and annual income to ensure you aren’t "over-insured." Generally, insurers prefer your total death benefit to stay within reasonable limits relative to your earnings. A common rule of thumb is that total coverage shouldn’t exceed 10 to 15 times your annual gross income, though this varies by carrier and age.
If you apply for a second policy, you must disclose existing coverage. Failing to do so can lead to claim denials later. The good news is that applying for a second policy usually doesn’t require a full medical exam if your first policy was recent and healthy. Some carriers offer accelerated underwriting for additional policies, using data from your previous application or electronic health records. This speeds up approval and saves you time.
Cost Implications: Is It Cheaper?
It depends on the size of the policies. Small policies have higher administrative fees per dollar of coverage. So, one $500,000 policy is often cheaper than five $100,000 policies. However, once you hit certain thresholds, the pricing curve flattens or even dips due to volume discounts. More importantly, laddering saves you money over time. Paying for a 30-year term policy when you only need 10 years of peak coverage wastes thousands of dollars in premiums.
| Feature | Single Large Policy ($800k) | Laddered Policies ($500k + $300k) |
|---|---|---|
| Initial Premium Cost | Higher (due to larger face value) | Lower (splitting reduces rate brackets) |
| Flexibility | All or nothing coverage | Drop coverage as needs decrease |
| Complexity | Simple management | Requires tracking multiple renewals |
| Best For | Static long-term needs | Changing financial responsibilities |
Potential Pitfalls to Avoid
While multiple policies offer flexibility, they add complexity. You must track renewal dates for each policy. Missing a payment on one could lapse that specific layer of protection without warning. Also, managing beneficiary designations becomes trickier. If you change your mind about who gets what, you have to update forms with every insurer individually. Keeping detailed records is essential.
Another issue is potential confusion during claims. If you pass away, your beneficiaries must file claims with every company. While insurers share data through the Medical Information Bureau (MIB) and other databases, they don’t always coordinate payments instantly. Beneficiaries might need to provide death certificates to three different companies instead of one. This administrative burden falls on grieving families, so clarity in your will and communication with loved ones is vital.
Who Should Consider Multiple Policies?
You likely benefit from stacking if:
- Your financial obligations change significantly over time (e.g., paying off a mortgage).
- You have complex assets, such as a business or rental properties, requiring specific liability coverage.
- You want to lock in insurability now for future needs via convertible term policies.
- You have pre-existing conditions that make large single-policy approvals difficult or expensive.
Conversely, stick to one policy if your needs are simple, static, and modest. One well-chosen term policy is easier to manage and often sufficient for average households. Don’t complicate things for the sake of complexity.
Frequently Asked Questions
Do I need to tell my current insurer about my new policy?
Yes. When applying for a new policy, you must list existing coverage. Similarly, some existing policies may have clauses requiring notification of significant changes in total insured value, though this is less common for standard consumer life insurance. Transparency prevents fraud accusations and ensures accurate underwriting.
Will having two policies double my payout?
Not necessarily. Each policy pays its stated death benefit independently. If you have a $200,000 policy and a $300,000 policy, your beneficiaries receive $500,000 total. However, insurers assess your total coverage against your income to prevent moral hazard. If you earn $50,000 a year, getting $5 million in coverage across two policies might raise red flags.
Is it better to buy one big policy or two smaller ones?
Two smaller policies are often better for laddering strategies because they allow you to drop coverage as debts decrease. One big policy is simpler to manage. Calculate the premium difference for your specific age and health profile. Often, the savings from laddering outweigh the slight increase in administrative hassle.
Can I cancel one policy if I buy another?
Yes, you can cancel any policy at any time. However, check for surrender charges on permanent policies. Term policies usually have no cancellation fees. Ensure you have new coverage active before canceling old coverage to avoid a gap in protection.
Does credit score affect multiple life insurance applications?
Indirectly, yes. Many insurers check credit history as part of underwriting. Poor credit can raise premiums on all your policies. Having multiple applications doesn’t hurt your credit score like loan inquiries do, but poor financial habits reflected in your credit report can impact your rates.