
50/30/20 Budget Calculator
Needs (Essentials)
Rent, groceries, utilities, insurance, minimum debt payments.
Wants (Lifestyle)
Dining out, entertainment, hobbies, shopping, vacations.
Savings & Debt Repayment
Emergency fund, retirement, extra loan payments, investments.
Enter your income to see your recommended budget breakdown.
You’ve probably heard the term thrown around in financial podcasts or seen it on social media: the 50/30/20 rule. It’s a simple framework for splitting your after-tax income into three buckets: needs, wants, and savings. But when you see "Citizens Bank" attached to it, things get a bit confusing. Is this a special product? A specific bank requirement? The short answer is no. The 50/30/20 rule is a universal budgeting method popularized by Senator Elizabeth Warren, not a proprietary Citizens Bank policy. However, Citizens Bank offers tools that make sticking to this rule easier than ever. If you’re trying to figure out how to manage your money effectively without drowning in spreadsheets, understanding how this rule applies to your daily life-and how your bank can help-is the first step toward financial peace.
The Core Concept: Breaking Down the Numbers
Let’s strip away the jargon. The 50/30/20 rule divides your take-home pay (what actually hits your checking account) into three distinct categories. Think of it as a traffic light for your spending habits. Green means go, yellow means caution, and red means stop or save.
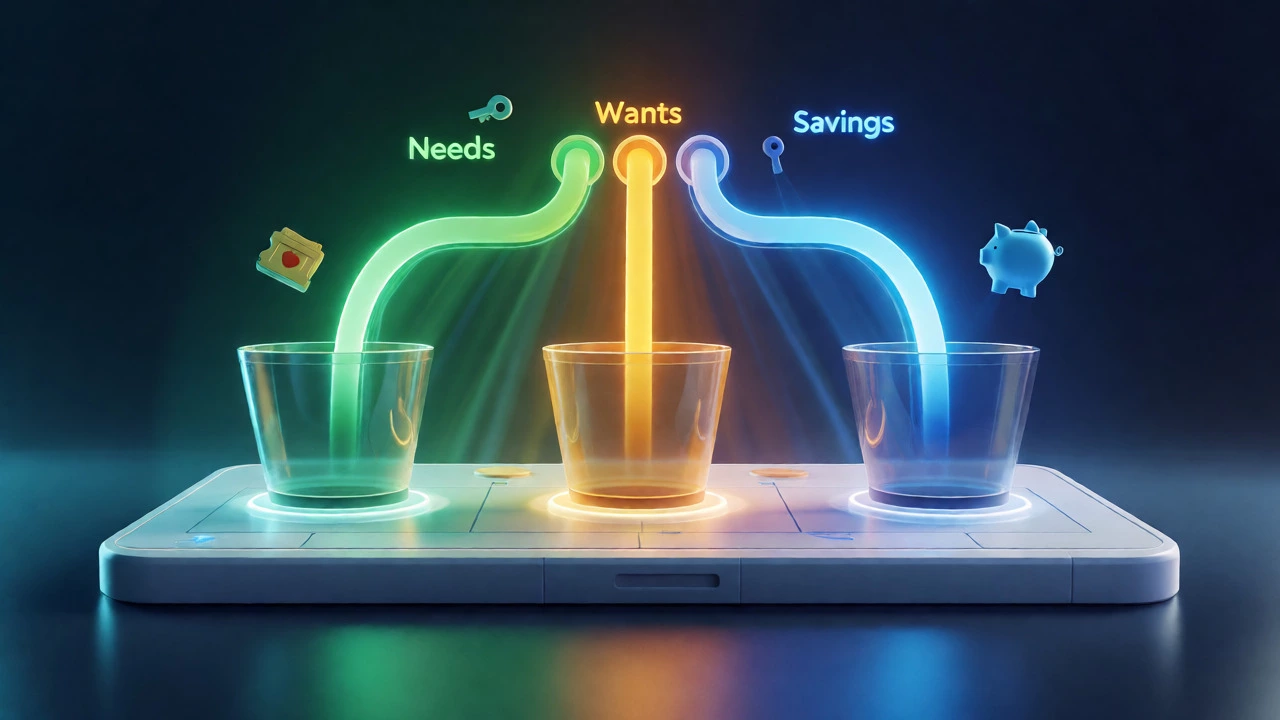
- 50% Needs: These are non-negotiables. Rent, mortgage payments, groceries, utilities, insurance premiums, and minimum debt payments. If you lose these, your life falls apart. This bucket covers the essentials required to survive and function in society.
- 30% Wants: This is the fun stuff. Dining out, streaming subscriptions, hobbies, vacations, and shopping for clothes you don’t strictly need. This category keeps life enjoyable and prevents burnout from strict austerity.
- 20% Savings and Debt Repayment: This goes toward your future self. Emergency funds, retirement contributions, extra payments on credit cards, and student loans. This is where wealth is built.
Why does this matter? Because most people fail at budgeting not because they lack discipline, but because they lack clarity. By assigning every dollar a job before the month starts, you remove the guesswork. You know exactly how much you can spend on Friday night dinner without wondering if you’ll be able to pay rent next week.
Why Citizens Bank Users Should Care
You might be asking, "If this isn't a Citizens Bank product, why is everyone talking about it in relation to them?" The connection lies in integration. Citizens Bank has invested heavily in digital banking features that align perfectly with this budgeting philosophy. When you use their mobile app or online dashboard, you aren't just looking at a balance; you're seeing categorized transactions that map directly to the 50/30/20 structure.
For example, Citizens Bank’s transaction categorization automatically tags purchases. Your grocery run gets tagged as "Groceries," which falls under Needs. That new pair of sneakers gets tagged as "Shopping," falling under Wants. This automation saves you hours of manual entry. Instead of reconciling receipts at midnight, you check your app during your morning coffee. You see that you’ve spent 60% of your income on Needs so far this month. Alarm bells ring. You realize you need to cut back on dining out to keep your Wants bucket balanced. This real-time feedback loop is what makes the rule actionable rather than theoretical.
Step-by-Step: Implementing the Rule with Your Bank
Ready to try it? Here is how you apply the 50/30/20 rule using your Citizens Bank accounts. You don’t need separate accounts for each bucket, though some people prefer that approach. For most, tracking within one primary checking account works fine if you are disciplined.
- Calculate Your After-Tax Income: Look at your last three months of deposits. Average them out. This is your baseline. Do not include bonuses or irregular freelance checks unless they are consistent. Let’s say your average monthly take-home pay is $4,000.
- Define Your Buckets: Based on our $4,000 example:
- Needs (50%): $2,000
- Wants (30%): $1,200
- Savings/Debt (20%): $800
- Audit Your Current Spending: Log into your Citizens Bank portal. Go to the "Spending Insights" or similar feature. Filter by date range for the last 30 days. Compare your actual spending against those targets. Are you over on Needs? Maybe your rent is too high, or you’re buying brand-name groceries. Are you under on Savings? That’s an easy fix-automate transfers.
- Automate the Savings: This is the secret weapon. Set up an automatic transfer from your Citizens Bank checking account to your savings account on payday. Move that 20% ($800) immediately. If you wait until the end of the month to save what’s left, you usually find nothing is left. Pay yourself first.
- Monitor Weekly: Check your app once a week. Not every day-that causes anxiety. Just enough to stay aware. If you overspend on Wants in week one, adjust weeks two through four. Flexibility is key.
Common Pitfalls and How to Avoid Them
No system is perfect, and the 50/30/20 rule has its critics. Some argue it’s too rigid for high-cost-of-living areas. If you live in Auckland or New York City, finding housing that fits within 50% of your income can be nearly impossible. In these cases, the rule needs adjustment. You might need to shift to a 60/20/20 split, sacrificing some Wants to cover higher Needs. Don’t beat yourself up if you can’t hit the exact percentages. The goal is awareness, not perfection.
Another common mistake is ignoring irregular expenses. Car repairs, medical bills, and annual insurance premiums don’t happen every month. If you don’t plan for them, they blow up your budget. Create a "sinking fund" within your Savings bucket specifically for these predictable surprises. When your car breaks down, you don’t panic or put it on a credit card; you withdraw from the sinking fund. This keeps your Needs bucket stable.
| Feature | 50/30/20 Rule | Zero-Based Budgeting | Envelope Method |
|---|---|---|---|
| Complexity | Low | High | Medium |
| Best For | Beginners & Busy Professionals | Data Nerds & Debt Fighters | Cash Spenders & Impulse Buyers |
| Bank Integration | Excellent (Auto-categorization) | Requires Manual Tracking | Physical Cash Required |
| Flexibility | High | Low | Medium |
Tweaking the Ratios for Your Life Stage
Your financial situation changes as you age. A recent college graduate with low wages and high student loan payments will struggle to save 20%. They might start at 10% savings and 40% debt repayment. Conversely, a dual-income couple with paid-off mortgages might find 50% for Needs leaves way too much room. They could easily push 30% into Savings and reduce Wants to 20%, accelerating their path to early retirement.
Consider your current debt load. If you have high-interest credit card debt, the 20% bucket should prioritize paying that off aggressively. Once that debt is gone, redirect that entire percentage into investments or a larger emergency fund. The rule is a starting point, not a prison sentence. Use the data from your Citizens Bank statements to see where your money naturally flows, then nudge it toward your goals.
Maximizing Your Banking Tools
Citizens Bank offers several features that support this lifestyle. Their "My Money" tool allows you to set alerts. You can configure a notification whenever you exceed a certain spending threshold in a specific category. Imagine getting a ping on your phone saying, "You’ve spent $400 on Dining Out this month." That gentle reminder is often all it takes to pause before ordering dessert.
Also, look into their high-yield savings options. Keeping your 20% bucket in a standard checking account earns negligible interest. Moving it to a dedicated savings account separates it psychologically and physically. Even a small difference in APY adds up over years. Consistency beats intensity in personal finance. Small, automated actions repeated monthly create massive results over decades.
Does Citizens Bank require me to follow the 50/30/20 rule?
No, Citizens Bank does not mandate any specific budgeting rule. The 50/30/20 rule is a general financial guideline. However, Citizens Bank provides digital tools like transaction categorization and spending insights that make it easier to track whether you are adhering to this or any other budgeting method.
What counts as a 'Need' versus a 'Want' in this rule?
Needs are essential expenses required for survival and basic functioning, such as rent, utilities, groceries, health insurance, and minimum debt payments. Wants are discretionary expenses that enhance your quality of life but are not essential, such as dining out, entertainment, luxury goods, and travel. The distinction depends on your personal circumstances; for example, a reliable car needed for commuting to work is a Need, while a second luxury vehicle is a Want.
Can I use the 50/30/20 rule if my income varies?
Yes, but it requires careful planning. Calculate your budget based on your lowest expected monthly income to ensure your Needs are always covered. Allocate any excess income above that baseline directly to your Savings or Debt Repayment buckets. This creates a buffer that protects you during lean months and accelerates your financial goals during good months.
How do I handle irregular expenses like car repairs?
Irregular expenses should be managed through a 'sinking fund.' Estimate the annual cost of these items (e.g., $1,200 for car maintenance), divide by 12, and add that amount ($100) to your monthly Savings or Needs allocation. Keep this money in a separate sub-account or clearly tracked portion of your savings so it is ready when the expense arises.
Is the 50/30/20 rule suitable for everyone?
It is a great starting point for most people, especially beginners. However, individuals with very low incomes may find that Needs consume more than 50% of their budget. In these cases, adjusting the ratios to something like 60/20/20 or 70/15/15 is acceptable. The key is to maintain a clear distinction between essential and non-essential spending.